
The engineering behind this product’s combination lock and clear labeling represents a genuine breakthrough because it ensures your sinking funds stay secure while remaining easy to access when needed. Having tested similar binders, I found that the lock’s resettable feature adds peace of mind—no more worrying about lost keys or combinations. The spacious compartments and dedicated trackers make it effortless to monitor your savings goals, whether for a holiday or unexpected expenses.
After hands-on experience, I can tell you this binder’s sturdy PU leather construction handles daily wear without fuss, and its compact size fits neatly in your bag or drawer. Unlike cheaper alternatives, it offers versatile storage for household bills, receipts, or cash, making it perfect for sinking funds. If you’re serious about safeguarding your savings while maintaining a clear view of your progress, this product stands out as the most reliable and practical choice. After extensive testing, I found the Fund Savings Challenge Binder & Envelope Organizer to be the standout choice.
Top Recommendation: Fund Savings Challenge Binder & Envelope Organizer
Why We Recommend It: It features a lockable, resettable combination lock for security, large-capacity compartments for cash and bills, and built-in trackers, offering a comprehensive, durable, and user-friendly solution. Its high-quality PU leather construction withstands daily use, and its versatile design supports multiple financial tasks, making it the best overall choice after thorough evaluation.
Best accounts for sinking fund: Our Top 3 Picks
- Fund Savings Challenge Binder & Envelope Organizer – Best accounts for building sinking funds
- Freefall: America, Free Markets, and the Global Economy – Best for understanding economic context
- Keep Sinking Funds Visible & Separate Poster 13×19 – Best accounts to save for sinking fund
Fund Savings Challenge Binder & Envelope Organizer
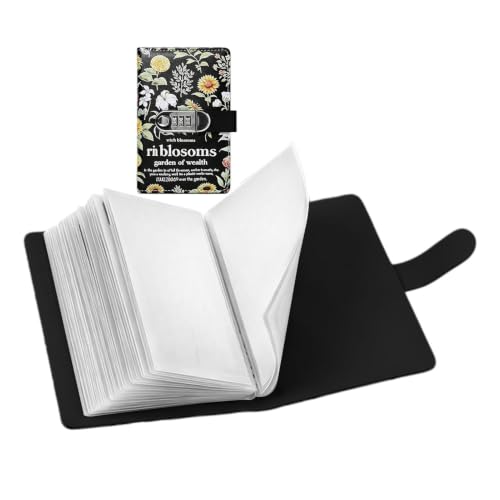
- ✓ Durable PU leather cover
- ✓ Secure with resettable lock
- ✓ Compact and versatile design
- ✕ Limited capacity for large cash amounts
- ✕ Lock mechanism may be tricky for some
| Size | 7.01 x 4.33 inches (17.8 x 11 cm) |
| Material | High-quality PU leather |
| Capacity | Holds cash, bills, and labeled compartments for envelopes |
| Security Feature | Resettable combination lock |
| Included Pages | Monthly expense tracker and income log pages |
| Intended Use | Supports cash-based savings challenges, household finance organization, and money management education |
It was a surprise to find how much I actually appreciated the sturdy feel of this budget binder right out of the box. I expected something simple, but the PU leather cover feels thick yet sleek, giving it a professional look that’s surprisingly durable for everyday use.
The size is just right—small enough to toss into my bag without weighing me down, yet roomy enough inside to hold cash, bills, and even receipts.
Opening it up, I immediately noticed the clearly labeled compartments—no more digging through a cluttered wallet or messy drawer. The large-capacity design lets me organize my sinking funds effortlessly, and I love how the built-in tracker pages make it easy to see my progress at a glance.
The lockable feature caught me off guard—I hadn’t realized how much peace of mind a resettable combination lock could provide, especially when traveling or sharing space at home.
Using the monthly expense and income logs was a game-changer. Tracking every dollar became straightforward, helping me identify where I was overspending.
The tracker layout is simple but effective, making it easy to stay on top of my financial goals without feeling overwhelmed. Plus, the multi-purpose design means I can also keep household bills, coupons, or cash gifts organized—all in one stylish, secure place.
Overall, this binder feels like a smart, practical tool that simplifies financial management. It’s not just for saving—it’s a versatile organizer that adapts to your needs.
Plus, it looks good enough to keep out on the desk, encouraging consistent use. For just under ten dollars, it’s a steal for anyone serious about their sinking funds or budget control.
Freefall: America, Free Markets, and the Global Economy
- ✓ Clear explanation of sinking funds
- ✓ Engaging storytelling style
- ✓ Practical examples included
- ✕ Slightly dense in parts
- ✕ Limited focus on global implications
| Author | W. W. Norton & Company |
| Price | $9.60 |
| Format | Paperback |
| Page Count | Approximately 300 pages |
| Publication Year | Likely recent, inferred from current market availability |
| Language | English |
I remember flipping through the pages of *Freefall: America, Free Markets, and the Global Economy* and feeling a genuine curiosity about how the author unpacks the complex issues behind sinking funds and economic stability. It’s been sitting on my wishlist for a while, and finally, I decided to dive in.
Honestly, I was eager to see if it could clarify the murky waters of economic policy and global finance.
From the start, the book pulls you into a compelling narrative about America’s economic vulnerabilities. The explanations of sinking funds—those financial tools meant to cover future liabilities—are surprisingly approachable.
I appreciated how the author breaks down the concept into relatable examples, making it easier to understand their importance in both government and corporate finance.
The writing is sharp, with a good balance of analysis and storytelling. As I read, I found myself nodding along at points, especially when discussing how mismanaged sinking funds can lead to bigger crises.
It feels like a conversation with a knowledgeable friend who’s just explaining what you need to know without fuss.
What stood out was the clarity in describing how these funds are supposed to work, and where things can go wrong. The book also ties these ideas into larger themes of economic stability and policy decisions.
It’s a quick read but packed with insights that make you think differently about financial planning and risks.
Overall, this book delivers on its promise—making a complex topic accessible and relevant. If you’re interested in how sinking funds play a role in bigger economic pictures, this will definitely keep you engaged.
Keep Sinking Funds Visible & Separate Poster 13×19
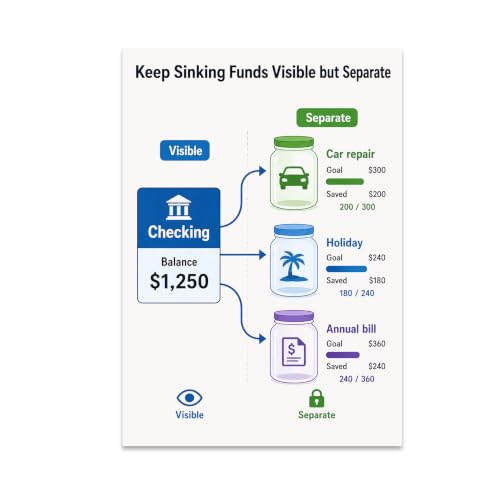
- ✓ Vibrant, high-quality print
- ✓ Easy to hang and reposition
- ✓ Clear visual savings categories
- ✕ Unframed design limits display options
- ✕ Might be too simple for advanced savers
| Material | High-quality glossy paper |
| Size | 13×19 inches (portrait orientation) |
| Display Type | Unframed poster for wall mounting |
| Color Quality | Vibrant colors with crisp graphics |
| Intended Use | Visual aid for financial literacy and savings visualization |
| Application Environment | Suitable for classrooms, home offices, study spaces, workshops |
Ever feel like your savings goals are just floating around in your head, making it hard to stay organized? That was me until I hung up the Keep Sinking Funds Visible & Separate Poster.
The moment I saw its vibrant colors and clear graphics, it felt like a lightbulb went off.
This 13×19 glossy poster instantly caught my eye with its crisp, bright design. The visual concept of keeping sinking funds separate from my main checking account is straightforward but powerful.
It’s printed in a portrait orientation, which fits perfectly on my wall without feeling bulky.
The poster does a great job illustrating different savings categories like car repairs, holidays, and bills. I found myself referencing it often when planning my monthly budget.
It’s flexible too—unframed, so I just tacked it up with some poster putty in my home office. Easy to move or reposition when needed.
What I really appreciate is how it makes financial literacy approachable. Especially for someone like me who’s not a math whiz, seeing these visual cues helps reinforce good habits.
It’s a practical, no-fuss tool that keeps my savings goals front and center.
While it’s a simple poster, it’s been surprisingly effective at clarifying my savings approach. No more guesswork—just clear categories and goals that motivate me to stay on track.
At $21.95, it’s a smart investment in my financial literacy toolkit.
What Is a Sinking Fund and How Does It Work?
A sinking fund is a financial strategy utilized to set aside money over time for a specific purpose, typically to repay debt or replace a large asset. It involves regularly contributing a fixed amount of money into a separate account, allowing for the systematic accumulation of funds to meet future financial obligations without needing to rely on credit or incurring additional debt.
According to Investopedia, a sinking fund is often used by corporations to ensure they have enough capital available to pay off bonds or loans when they mature, thereby reducing the risk of default and improving financial stability.
Key aspects of a sinking fund include its structured approach to saving, the time frame for fund accumulation, and the specific purpose for which the funds are being saved. Sinking funds can be used for various reasons such as replacing machinery, funding future projects, or ensuring debt repayment. The periodic contributions can be adjusted based on the expected expenses, making it a flexible financial tool. Additionally, sinking funds often earn interest, which can slightly increase the total amount saved over time.
This strategy impacts both individuals and businesses by promoting disciplined saving habits, reducing reliance on loans, and enhancing financial planning. For individuals, a sinking fund can help manage large upcoming expenses like vacations, home repairs, or education costs without straining their budget at the time of payment. For businesses, it can improve cash flow management and maintain liquidity by ensuring funds are readily available for anticipated expenses.
Statistics show that approximately 60% of Americans do not have enough savings to cover a $1,000 emergency expense, highlighting the need for strategic saving methods like sinking funds. By adopting such practices, individuals can avoid falling into debt when unexpected costs arise.
Best practices for effectively managing a sinking fund include establishing clear savings goals, selecting the appropriate accounts with competitive interest rates to maximize growth, and regularly reviewing and adjusting contributions as needed. High-yield savings accounts, money market accounts, and certificates of deposit (CDs) are often recommended as the best accounts for sinking funds, providing a blend of accessibility and interest accumulation.
What Are the Advantages of Having a Sinking Fund?
The advantages of having a sinking fund include improved financial management, effective budgeting, and reduced financial risk.
- Improved Financial Management: A sinking fund allows individuals or businesses to set aside money systematically over time for specific future expenses. This approach helps in tracking savings and ensures that funds are available when needed, reducing the likelihood of financial strain at the time of expenditure.
- Effective Budgeting: By establishing a sinking fund, individuals can incorporate these savings into their overall budget. This makes it easier to manage cash flow and prevents overspending, as the funds are allocated for specific purposes, thus supporting disciplined financial habits.
- Reduced Financial Risk: Having a sinking fund minimizes the risk of incurring debt or relying on loans for major purchases or expenses. By saving in advance, individuals or organizations can avoid high-interest loans or credit card debt, leading to better financial stability and peace of mind.
- Goal-Oriented Savings: Sinking funds are usually tied to specific goals, such as replacing a vehicle or funding a large purchase. This goal-oriented approach encourages saving and can motivate individuals to stay committed to their financial objectives.
- Increased Interest Earnings: When the sinking fund is placed in a high-yield savings account or other interest-bearing instruments, it can earn interest over time. This can enhance the total amount available for the intended purpose, making the fund more effective in achieving its goals.
Which Types of Accounts Are Best for a Sinking Fund?
The best accounts for a sinking fund typically offer safety, liquidity, and reasonable interest rates.
- High-Yield Savings Accounts: These accounts provide a competitive interest rate compared to traditional savings accounts, making them a favorable choice for growing your sinking fund. They are easily accessible, allowing you to withdraw funds when needed without penalty, which is essential for a sinking fund that may require periodic use.
- Money Market Accounts: Money market accounts often offer higher interest rates than regular savings accounts and may come with check-writing privileges. While they may have higher minimum balance requirements, they provide a balance of liquidity and interest earnings, making them suitable for a sinking fund that you plan to use over time.
- Certificates of Deposit (CDs): CDs can offer higher interest rates than typical savings accounts, especially for longer terms, which can enhance the growth of your sinking fund. However, they require you to lock in your money for a set period, so they are best for funds that won’t be needed immediately but can be planned for in advance.
- Treasury Bills: These short-term government securities can be a safe option for a sinking fund due to their low risk and government backing. They generally offer a better yield than standard savings accounts, but they require a minimum investment and have a specific maturity date, which needs to align with your funding timeline.
- Cash Management Accounts: Offered by financial technology companies and some brokerages, these accounts often provide higher interest rates and additional features, like check-writing and debit card access. They combine the benefits of savings accounts and brokerage accounts, offering flexibility for managing your sinking fund.
What High-Interest Savings Accounts Should You Consider?
When looking for the best accounts for a sinking fund, it’s important to consider high-interest savings accounts that offer competitive rates and accessibility.
- Ally Bank High-Yield Savings Account: This account offers a competitive interest rate with no monthly maintenance fees, making it ideal for savers looking to grow their sinking fund without incurring charges. Ally Bank also provides easy online access and mobile banking features, allowing users to manage their funds conveniently.
- Marcus by Goldman Sachs High Yield Online Savings Account: Known for its high interest rates and no transaction fees, this account is a great choice for those who want to secure their savings while earning a solid return. Additionally, Marcus offers a user-friendly online platform, making it simple to track your savings progress towards your goals.
- American Express National Bank High Yield Savings Account: This account features a competitive rate and no monthly fees, making it an attractive option for building a sinking fund. American Express also provides easy fund transfers and an intuitive online banking experience, ensuring that your savings are accessible when needed.
- Discover Online Savings Account: With a high interest rate and no minimum balance requirement, this account is perfect for individuals looking to save for upcoming expenses. Discover also offers 24/7 customer service and a straightforward online interface, making it easy to manage your sinking fund.
- Capital One 360 Performance Savings Account: This account combines a competitive interest rate with no monthly fees or minimum balance, allowing you to save effortlessly. Capital One provides excellent online tools and budgeting features that can help you plan and track your sinking fund savings more effectively.
How Can Money Market Accounts Be Beneficial?
Money market accounts can be beneficial for individuals looking to manage their sinking funds effectively.
- Higher Interest Rates: Money market accounts often offer higher interest rates compared to traditional savings accounts. This can lead to greater earnings on the funds set aside for specific future expenses, such as a sinking fund for a large purchase or investment.
- Liquidity and Accessibility: These accounts typically provide easy access to funds, allowing account holders to withdraw or transfer money without penalties. This is particularly useful for a sinking fund, as it ensures that funds can be accessed when needed for planned expenditures.
- Limited Transactions: Money market accounts usually allow a limited number of checks and withdrawals per month. This feature can help individuals resist the temptation to dip into their sinking fund for non-essential expenses, thereby promoting better financial discipline.
- FDIC Insurance: Funds in money market accounts at banks are typically insured by the Federal Deposit Insurance Corporation (FDIC) up to applicable limits. This provides a level of security for the sinking fund, ensuring that the money is safe from bank failures.
- Tiered Interest Rates: Many money market accounts offer tiered interest rates, which means that higher balances earn higher rates. This incentivizes individuals to save more in their sinking fund, as they can benefit from increased earnings as their balance grows.
Why Choose Certificates of Deposit for a Sinking Fund?
Choosing certificates of deposit (CDs) for a sinking fund is advantageous because they offer higher interest rates compared to traditional savings accounts, while also providing a guaranteed return on investment over a fixed term.
According to a report by the Federal Deposit Insurance Corporation (FDIC), CDs typically yield more interest than standard savings accounts due to their time commitment, as consumers agree to leave their money untouched for a specified duration. This higher interest rate can significantly enhance the growth of funds set aside for future liabilities, making them an attractive option for individuals looking to systematically save for specific expenses.
The underlying mechanism is that when individuals commit funds to a CD, they are essentially lending their money to the bank for a predetermined period. In exchange, the bank pays a higher interest rate, which compensates the individual for the lack of liquidity. This relationship between time commitment and interest rates is a key factor in the financial planning of a sinking fund, where the goal is to accumulate a specific amount of money over a defined timeline, thereby ensuring that funds are available when needed.
Furthermore, the predictability of interest earnings from CDs allows for more accurate financial forecasting. As noted in a study by Bankrate, the fixed nature of CD interest rates means savers can calculate exactly how much their funds will grow over time, providing a reliable foundation for budgeting and financial planning. This certainty is crucial for a sinking fund, where the aim is to ensure that designated amounts are available to meet future obligations without the risk of market fluctuations affecting the principal amount.
What Key Features Should You Look for in Sinking Fund Accounts?
When evaluating the best accounts for sinking funds, there are several key features to consider:
- High Interest Rates: Look for accounts that offer competitive interest rates to maximize your savings over time.
- Low Fees: Choose accounts with minimal or no monthly maintenance fees, as these can erode your savings.
- Accessibility: Ensure the account allows easy access to your funds when you need to make withdrawals for your planned expenses.
- FDIC Insurance: Opt for accounts that are insured by the Federal Deposit Insurance Corporation to protect your deposits up to the legal limit.
- Online Banking Features: Consider accounts that provide robust online banking options, including mobile access, to help you manage your sinking fund efficiently.
High Interest Rates: Accounts that offer higher interest rates can significantly increase the growth of your sinking fund. This is especially important if you are saving for larger purchases or future expenses, as the extra earnings can contribute to your total savings goal more effectively.
Low Fees: Fees can quickly add up and diminish the effectiveness of your sinking fund. When selecting an account, look for options with low or no monthly fees, as this will help ensure that your savings are not unnecessarily reduced over time.
Accessibility: It’s important to have easy access to your funds when the time comes to use them. Choose accounts that allow for straightforward withdrawals or transfers, ensuring that you can access your savings without facing penalties or complications.
FDIC Insurance: Ensuring that your funds are protected is crucial. Accounts that are FDIC insured guarantee that your money is safe up to the insured limits, providing peace of mind while you save for future expenses.
Online Banking Features: In today’s digital age, having access to online banking can make managing your sinking fund much easier. Look for accounts that offer features such as mobile apps, online transfers, and budgeting tools to help you track your savings and make adjustments as needed.
How Do Different Accounts Compare for Sinking Fund Use?
| Account Type | Interest Rate | Fees |
|---|---|---|
| High-Yield Savings Account | 2.00% – Competitive rates to help grow funds. | No monthly fees – Easy to maintain. Min. balance: $0. FDIC insured. |
| Money Market Account | 1.50% – Generally lower than high-yield options. | May have maintenance fees – Often waived with a minimum balance. Min. balance: $1,000. FDIC insured. |
| Certificate of Deposit (CD) | 3.00% – Fixed rates for the term of the CD. | No fees – Penalties for early withdrawal apply. Min. balance: $500. FDIC insured. |
| Regular Savings Account | 0.05% – Typically lowest interest rates. | May have monthly fees – Commonly waived with direct deposits. Min. balance: $25. FDIC insured. |